AI is moving quickly from the edge of payments into the mainstream. In June, Visa announced new AI, stablecoin and token capabilities designed to support agentic commerce, where AI agents can help initiate and complete transactions. Mastercard also launched Agent Pay for Machines, aimed at enabling secure, always-on machine-led payments across cards, accounts and stablecoins.
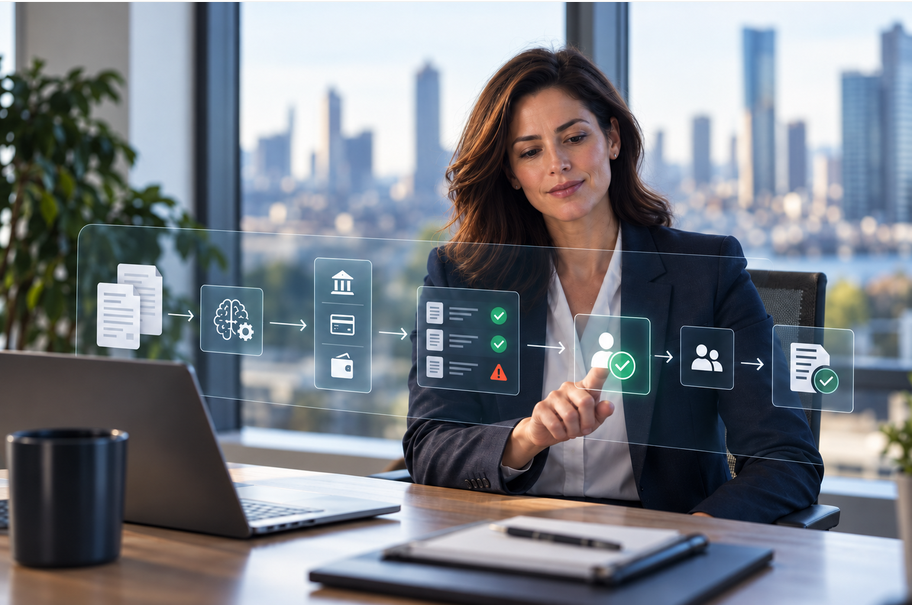
These developments matter because they show where the industry is heading. Payments are becoming faster, more automated and increasingly embedded into software, systems and workflows. For B2B payments, the opportunity is clear: AI could help businesses review invoices, identify the right payment method, spot exceptions, support reconciliation and reduce manual administration. For finance teams managing complex supplier relationships and thousands of transactions, this could be hugely valuable.
But potential is not the same as readiness. B2B payments are rarely simple. A payment is not just money moving from one account to another. It is part of a wider business process involving approvals, supplier preferences, settlement timing, refunds, reconciliation, fraud controls, compliance responsibilities and internal governance.
“AI will have a major impact on payments, but businesses should be careful not to confuse automation with understanding,” says Pat Bermingham, CEO of Adflex. “In B2B payments, the hard part is often not pressing the button. It is knowing which button should be pressed, why, and what happens if something goes wrong.”
Used well, AI could remove friction from repetitive tasks and help finance teams make faster, better-informed decisions. Used poorly, it could create new risks: payments triggered without enough context, exceptions missed, accountability blurred, and customers left trying to resolve problems without access to someone who understands the payment flow. The lesson is simple: automation should not mean abandonment.
Many businesses already find payments more complicated than they should be. They may be working across multiple systems, different payment methods, supplier-specific requirements and internal processes that have evolved over years. When something fails, the issue may sit between a gateway, acquirer, ERP system, file format or supplier process. In that environment, self-service technology has real value, but it cannot be the whole answer.
Businesses need modern tools, flexible APIs and automated payment infrastructure. But they also need access to people who can explain a payment flow, investigate an issue and help them make the right operational decision. This will become even more important as AI-led payments develop.
If AI agents are going to initiate payments, businesses will need strong guardrails. They will need to define who or what is authorised to make a payment, under what conditions, to which suppliers, using which methods and within which limits. They will also need clear audit trails, exception handling and escalation routes. The technology may be new, but the commercial requirement is familiar: control.
“The future of payments will not be fully manual, but it should not be blindly automated either,” adds Bermingham. “The right model is technology supported by people who understand payments deeply enough to help customers make sense of complexity.”
For businesses, the priority should be getting the foundations right before expecting AI to transform payment operations. Are payment flows clear? Are supplier preferences properly captured? Is reconciliation data consistent? Are approval rules documented? Can exceptions be identified quickly? Does everyone know where responsibility sits when something goes wrong? If the answer is no, AI risks accelerating confusion rather than solving it.
If the foundations are strong, however, the opportunity is significant. AI could help businesses move from reactive payment management to more intelligent, proactive payment operations. It could recommend the best payment route based on cost, timing and acceptance. It could flag unusual behaviour before money moves. It could surface the right information at the right point in the workflow.
But the aim should always be the same: making payments easier to manage, not harder to understand. At Adflex, our view is that payments work best when technology and human expertise reinforce each other. Automation should reduce unnecessary effort. APIs should make integration easier. Self-service tools should give customers more control. But when a business needs help understanding a payment issue or designing a better payment flow, they should still be able to speak to a real person.
AI will change the payments industry. In time, it may change it profoundly. But the businesses that benefit most will not be those that remove people from the process entirely. They will be those that use AI to support better decisions, stronger controls and simpler operations.
AI-led payments are coming. The question is whether they will make business payments simpler, or simply add another layer of complexity. The answer will depend on how carefully the industry builds them, and whether businesses remember that in complex payments, expertise still matters.
Pat Bermingham is CEO at Adflex. He has over 25 years' experience in the payments industry, overseeing the growth and development of Adflex as a premier B2B payments service provider.